Texas Total Loss Threshold: The 100% Rule and How to Fight a Lowball Offer
Texas brands a vehicle salvage only when repairs exceed its full actual cash value. Insurers routinely total vehicles well below that line, and the offer is often low. We use the Appraisal Clause to close the gap.
Texas Total Loss Appraisal Clause Services
Settling a total loss claim in the Lone Star State takes market data that national valuation reports routinely miss. Texas is not one market: a pickup’s value in Midland, Lubbock, or Amarillo can differ sharply from the same truck in Dallas, Houston, or San Antonio, and a valuation built on mismatched comparables shows it. Whether your vehicle was wrecked on I-35, I-10, I-45, or I-20, or totaled by hail or flood, accepting your insurer’s first offer is a mistake. Ironclad Claims Solutions helps Texas drivers invoke the appraisal clause in their auto policies and pursue a binding award based on real market data. Our founder, Joshua Dorris, has served as a testifying expert in Texas state and federal courts.
Understanding the Texas Total Loss Threshold.
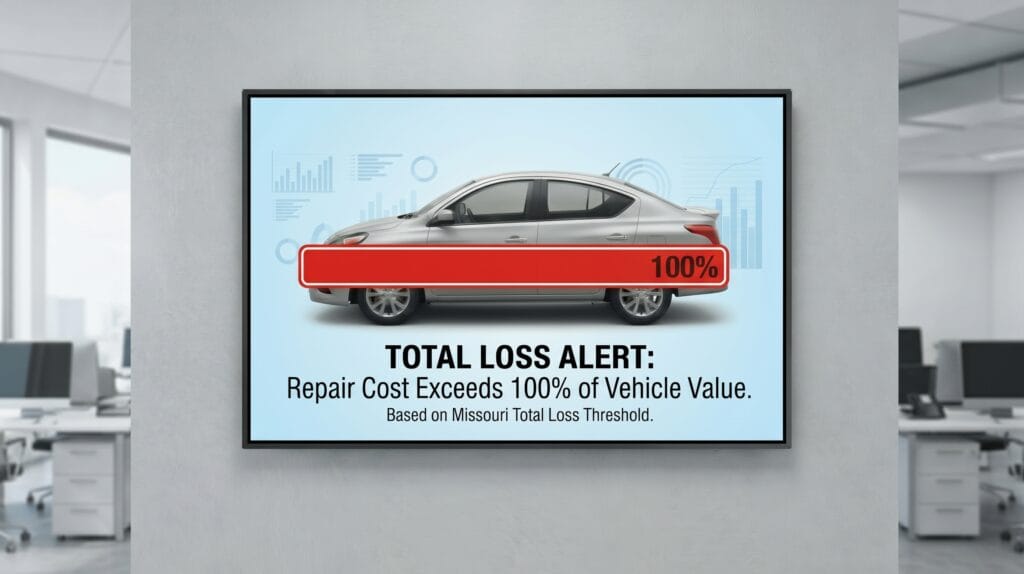
Texas sets its threshold in Tex. Transp. Code § 501.091. A vehicle is a salvage motor vehicle when the cost of repairs exceeds its actual cash value immediately before the damage. In other words, the legal line is 100% of the vehicle’s value, one of the highest in the country. The repair cost counts parts and labor but excludes the materials and labor for repainting and the sales tax on the repairs. Texas defines actual cash value as the vehicle’s market value.
Because the legal line is so high, most Texas total losses are an insurer’s business decision, not a legal requirement. Many insurers total a vehicle once the repair estimate plus the salvage value approaches its actual cash value, so your car can be totaled with damage well under 100% of its value. That makes the valuation the whole fight.
Once a total loss is declared, insurers often rely on third-party valuation software that pulls comparables from mismatched markets, misses trim levels and options, or applies lump-sum condition deductions that are never itemized. In a state as large as Texas, a comparable from a different region can move a valuation by thousands of dollars.
Activating the appraisal clause introduces an independent, certified appraiser to legally establish and mandate your vehicle’s true pre-accident worth.
Comparing states? See our total loss threshold by state guide for the rule in all 50 states.
Can You Dispute a Total Loss Offer in Texas?
The Right to Your Own Appraisal: You are not required to accept the insurance company’s first offer.
- The Appraisal Clause: If you and your insurer disagree on the value, you can invoke the “Appraisal Clause” and hire an independent appraiser (Ironclad Claims) to demand a fair settlement.
- Texas SB 458: Texas law (Tex. Ins. Code ch. 1813) now requires personal auto policies delivered, issued, or renewed on or after January 1, 2026 to include an appraisal provision. Either side can demand appraisal when you disagree on the amount of loss, including total losses, and the award is binding on that amount. Older policies depend on their own language, so send us yours and we’ll check.
Valuing Totaled Vehicles Across Texas Markets
Texas has several large, distinct vehicle markets: Dallas–Fort Worth, Houston, San Antonio, and Austin each have deep dealer inventory, and prices for the same vehicle can differ between them. In a metro market, a fair valuation should draw on comparables a buyer could actually shop in that metro. We review whether the insurer’s comparables reflect your market, or whether they lean on lower-priced listings from wherever the software found them.
In West Texas, the Panhandle, and rural areas, local inventory is often too thin to value a vehicle on its own, and comparables have to come from Lubbock, Amarillo, Midland–Odessa, or farther away. That is legitimate, but each comparable still has to match your vehicle’s trim, options, mileage, and condition, with every adjustment supported by market data. See our Oklahoma and Arkansas pages for neighboring markets.
Why we outperform the competition
We know the Texas market.
Local Market Data
We don't use national averages. We look at actual sales data from your Texas market to prove your car's value.
Expert Negotiation
We handle the "Umpire" process and communication with the insurance company.
Proven Results
Our clients see an average increase of $2,500 – $4,500 over the initial insurance offer.
How to dispute a total loss offer
- Contact Ironclad Claims Solutions for a free claim review to determine how much more we can increase your settlement.
- After the review, we will assist you with invoking your right to appraisal with your insurance company.
- Your insurance company will then be forced to step out of negotiations and hire a third-party independent appraiser who will work with us to reach an agreement on the value of your vehicle.
Total Loss FAQs
What is the total loss threshold in Texas?
Texas uses 100% of actual cash value. Under Tex. Transp. Code § 501.091, a vehicle is a salvage motor vehicle when the cost of repairs, excluding repainting and sales tax, exceeds its value immediately before the damage. Insurers can and often do declare a total loss well below that point.
Do Texas auto policies have an appraisal clause?
Under SB 458 (Tex. Ins. Code ch. 1813), personal auto policies delivered, issued, or renewed on or after January 1, 2026 must include an appraisal provision. Either side can invoke it when you disagree on the amount of loss, including total losses, and the award is binding on that amount. For older policies, it depends on the policy language. Send us yours and we'll check.
How long do I have to dispute a total loss offer in Texas?
Act quickly. Texas appraisal rules set deadlines for demanding appraisal that start when your insurer accepts coverage, and your policy may set its own deadlines. Don't sign a release or cash a settlement check before getting a free claim review.