Arkansas Total Loss Threshold: The 70% Rule and How to Fight a Lowball Offer
Arkansas brands a vehicle salvage when damage reaches 70% of its average retail value, or when it’s water damaged. Your insurer can still total it below that line, and the offer is often low. We use the Appraisal Clause to close the gap.
Arkansas Total Loss Appraisal Clause Services
Settling a total loss auto insurance claim in the Natural State requires precise regional market data that national insurance providers routinely ignore. Whether your vehicle was severely damaged on a major transit corridor like I-40, a high-traffic metro highway in Little Rock, or during severe regional weather in Northwest Arkansas, accepting your insurance company’s initial valuation offer is a mistake. Insurance adjusters consistently rely on automated, generalized valuation reports that fail to reflect the actual cash value of well-maintained vehicles in our unique state market. At Ironclad Claims Solutions, we specialize in helping Arkansas drivers invoke the appraisal clause built directly into their auto policies, stripping the negotiation power away from the insurance adjuster and demanding a binding settlement based on true local data.
Understanding the Arkansas Total Loss Threshold.
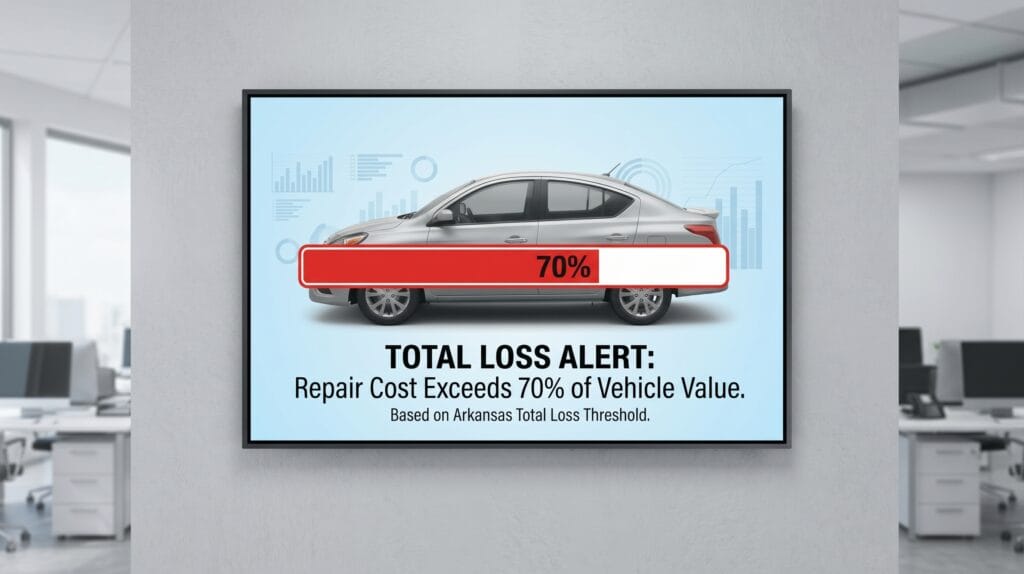
Arkansas uses a fixed 70% threshold. Under Ark. Code § 27-14-2301, a vehicle becomes a salvage vehicle when its damage equals or exceeds 70% of its average retail value, or when it has been water damaged to the extent defined by the statute. The threshold decides when a vehicle must be branded salvage. It does not prevent your insurer from declaring a total loss at a lower percentage.
Once a total loss is declared, insurers often deploy flawed third-party valuation software to lower their payouts. These programs routinely pull mismatched “comparable” vehicles from outside your immediate driving region or apply subjective, penalizing condition deductions to lower your vehicle’s pre-accident value.
Activating the appraisal clause introduces an independent, certified appraiser to legally establish and mandate your vehicle’s true pre-accident worth.
Comparing states? See our total loss threshold by state guide for the rule in all 50 states.
Can You Dispute a Total Loss Offer in Arkansas?
The Right to Your Own Appraisal: You are not required to accept the insurance company’s first offer.
- The Appraisal Clause: Most Arkansas policies contain an “Appraisal Clause.” If you and the insurer disagree on the value, you can hire an independent appraiser (Ironclad Claims) to demand a fair settlement.
- Sales Tax & Fees: In Arkansas, the insurer must include applicable sales tax, title, and registration fees in the total loss settlement.
Water Damage and Total Losses in Arkansas
Arkansas is one of the states where water damage is its own path to a salvage title, separate from the 70% repair-cost test. After flooding or heavy storms, flood-damaged vehicles are often totaled even when the repair estimate looks modest, because water intrusion affects wiring, electronics, and safety systems in ways that are hard to fully repair. If your vehicle was totaled after water damage, the settlement still has to reflect its true pre-loss value, and the appraisal clause gives you a way to dispute it.
Valuing Totaled Vehicles Across Arkansas Markets
Arkansas vehicle markets center on Little Rock, Northwest Arkansas, and Fort Smith, with much of the state depending on those areas or on neighboring states for comparable vehicles. Fort Smith and Northwest Arkansas sit along the Oklahoma line, so valuations there may reasonably include Oklahoma listings, but every comparable still has to match your vehicle’s trim, options, mileage, and condition. We check where each of the insurer’s comparables came from and whether it is a genuine match. See our Oklahoma and Missouri pages for neighboring markets.
Why we outperform the competition
We know the Arkansas market.
Local Market Data
We don't use national averages. We look at actual sales data from Arkansas to prove your car's value.
Expert Negotiation
We handle the "Umpire" process and communication with the insurance company.
Proven Results
Our clients see an average increase of $2,500 – $4,500 over the initial insurance offer.
How to dispute a total loss offer
- Contact Ironclad Claims Solutions for a free claim review to determine how much more we can increase your settlement.
- After the review, we will assist you with invoking your right to appraisal with your insurance company.
- Your insurance company will then be forced to step out of negotiations and hire a third-party independent appraiser who will work with us to reach an agreement on the value of your vehicle.
Total Loss FAQs
What is the total loss percentage in Arkansas?
Arkansas does not use a fixed statutory percentage threshold like Oklahoma's 70%. Instead, Arkansas follows the Total Loss Formula (TLF). A vehicle is legally declared a total loss when the estimated cost of repairs plus the vehicle’s remaining salvage value equals or exceeds its actual cash value (ACV) before the accident.
Does Arkansas require insurance to pay sales tax on totaled cars?
Yes. Under Arkansas Insurance Department regulations (Rule and Regulation 43), when an insurance company settles a total loss claim on a market-value basis, they are required to compensate you for the mandatory state and local sales taxes, title fees, and registration transfer fees necessary for you to purchase a replacement vehicle.
How long do I have to dispute a total loss claim in Arkansas?
While it is always best to invoke your policy's appraisal clause as quickly as possible to avoid storage fees and delays, the statute of limitations for filing a property damage lawsuit or formally disputing an auto insurance claim settlement in Arkansas is generally three (3) years from the date of the accident.