Don't Let Insurance Companies Lowball Your Oklahoma City Total Loss Claim.
In Oklahoma City, the law is on your side, but the insurance company isn’t. We use the Appraisal Clause to bridge the gap between their offer and your car’s actual value.
Oklahoma City Total Loss Claim
Navigating a vehicle total loss settlement in the state’s largest metropolitan hub comes with unique challenges. Whether your vehicle was severely damaged in a multi-car collision on I-40 near the downtown junction, a high-speed accident on the John Kilpatrick Turnpike, or a severe seasonal hailstorm in Northwest OKC, recovering what your car is actually worth requires an aggressive strategy. Insurance adjusters often rely on sweeping national software data that fails to reflect the fast-moving automotive market right here in central Oklahoma. At Ironclad Claims Solutions, we leverage the appraisal clause in your auto policy to take the negotiation out of the adjuster’s hands and force a payout that reflects true Oklahoma City market data.
Understanding the Oklahoma City Total Loss Threshold.
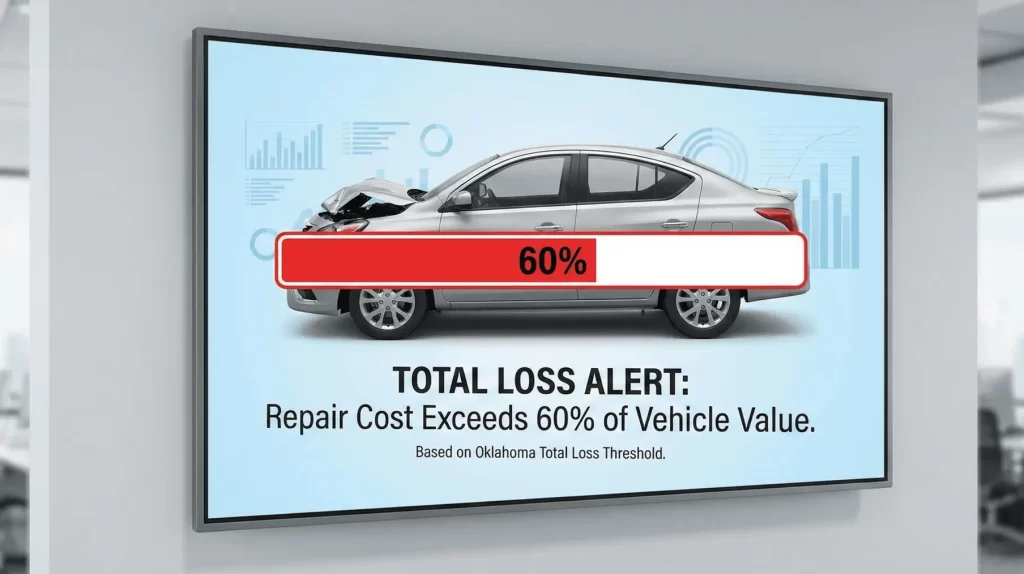
Under Okla. Stat. tit. 47, § 1111, a vehicle must receive a salvage title when repair costs exceed 60% of its fair market value, a threshold that rises to 70% on November 1, 2026 under Senate Bill 1920. The threshold governs salvage branding; insurers can still declare a total loss below it. In a heavy commuter metro like Oklahoma City, where daily travel spans from Edmond to Moore, frame and mechanical damage from highway accidents easily push repair estimates past this mark.
When this happens, insurers frequently use flawed valuation reports (like CCC ONE) that downgrade your vehicle’s pre-accident condition or select poor “comparable” vehicles from outside the OKC metro to save themselves money.
Invoking the appraisal clause stops the lowball cycle by introducing independent, certified appraisers to mandate an accurate, legally binding valuation.
Can You Dispute a Total Loss Offer in Oklahoma City?
The Right to Your Own Appraisal: You are not required to accept the insurance company’s first offer.
- The Appraisal Clause: Most OK policies contain an “Appraisal Clause.” If you and the insurer disagree on the value, you can hire an independent appraiser (Ironclad Claims) to demand a fair settlement.
- Sales Tax & Fees: In Oklahoma City, the insurer must include applicable sales tax, title, and registration fees in the total loss settlement.
How Insurers Value Totaled Cars in the Oklahoma City Market
The Oklahoma City metro is the largest vehicle market in the state, which gives insurers plenty of comparable vehicles to choose from, and they don’t always choose fairly. Because the metro spans Oklahoma, Cleveland, and Canadian counties, valuation reports can pull comps from wherever prices are lowest rather than from where a buyer would realistically shop.
Central Oklahoma’s hail season adds another problem. Insurers often take condition deductions for prior hail damage, sometimes on vehicles that were repaired or never damaged. Our Oklahoma City appraisals document your vehicle’s actual pre-loss condition and use properly matched local comparables, with no inflated deductions and no apples-to-oranges comps. If you live in the suburbs, see our Edmond, Moore, Midwest City, and Norman pages.
If Your Dispute Ends Up in Court
Most appraisal disputes end with a binding award, but appraisers decide only the amount of the loss. Coverage denials, or an insurer refusing to pay an award, go to the district court in your county. For Oklahoma City, that’s the Oklahoma County District Court at 321 Park Avenue; Cleveland County cases go to Norman and Canadian County cases to El Reno. Claims of $10,000 or less can use the small claims docket. For larger disputes, talk with an attorney.
Why we outperform the competition
We know the Oklahoma City market.
Local Market Data
We don't use national averages. We look at actual sales data from OKC to prove your car's value.
Expert Negotiation
We handle the "Umpire" process and communication with the insurance company.
Proven Results
Our clients see an average increase of $2,500 – $4,500 over the initial insurance offer.
How to dispute a total loss offer
- Contact Ironclad Claims Solutions for a free claim review to determine how much more we can increase your settlement.
- After the review, we will assist you with invoking your right to appraisal with your insurance company.
- Your insurance company will then be forced to step out of negotiations and hire a third-party independent appraiser who will work with us to reach an agreement on the value of your vehicle.
Total Loss FAQs
What is the total loss percentage in Oklahoma City?
It is 60%. If repairs exceed 60% of the value, it’s a total loss.
Does Oklahoma City require insurance to pay sales tax on totaled cars?
Yes, Oklahoma City law requires insurers to compensate you for sales tax and licensing fees.
How long do I have to dispute a claim in Oklahoma City?
While you should act fast, the statute of limitations for property damage in Oklahoma City is generally two years.